The AI Trade Nobody Is Talking About 🚨
When investors think about AI stocks, names like Nvidia, Microsoft, and Alphabet dominate the conversation. But there is a quieter, arguably more indispensable player hiding in plain sight: ASML (NASDAQ: ASML).
ASML is the world's only commercial supplier of extreme ultraviolet (EUV) lithography systems — the machines that print the tiny patterns on silicon wafers that become the transistors powering every advanced AI chip. Without ASML, there is no Blackwell. No Vera Rubin. No next-generation AI at all.
📌 Key takeaway: If you believe AI compute demand keeps compounding, you have to care about the company that makes the machines that make the chips.
Why the Moat Is Nearly Unbreakable
ASML's competitive position is not just strong — it is structurally unique. The company spent decades and billions of euros to commercialize EUV, and no competitor has managed to replicate it at scale.
The Customer List Says Everything
- TSMC — the world's leading foundry — depends on ASML for leading-edge nodes
- Samsung — integrating High-NA EUV into advanced DRAM by 2028
- Intel Foundry — already processed over 1 million wafers using High-NA EUV across testing, development, and production, including selected layers of Panther Lake processors
The Next Leg: High-NA EUV
In September, ASML announced an expanded collaboration with Intel Foundry to accelerate High-NA EUV adoption. TSMC is targeting high-volume manufacturing with High-NA EUV for advanced nodes beginning in 2030. This is not a one-quarter story — it is a decade-long capex cycle.
💡 Insight from the data: ASML's gross margin sits near 52.7%, which is unusual for a capital equipment maker. That pricing power is the fingerprint of a true monopoly.
The Numbers Behind the Hype
ASML reports Q3 results on October 14, and the setup is compelling.
| Metric | Q3 2026 (Est.) | Q3 2025 | YoY Change |
|---|---|---|---|
| Revenue | €11.68B | ~€7.5B | +55% |
| EPS | €10.66 | €5.49 | +94% |
| Q2 Net Income | €2.9B | €2.3B | +26% |
| Gross Margin | 52.73% | — | — |
| Market Cap | $686B | — | — |
| Dividend Yield | 0.51% | — | — |
The Bear Case Is Not Trivial 🐻
- Semiconductor spending cycles — capex is lumpy, and downturns hit hard
- Export restrictions — geopolitics remains a wild card, especially around China
- R&D cost escalation — each new node gets exponentially more expensive to enable
Technical Context
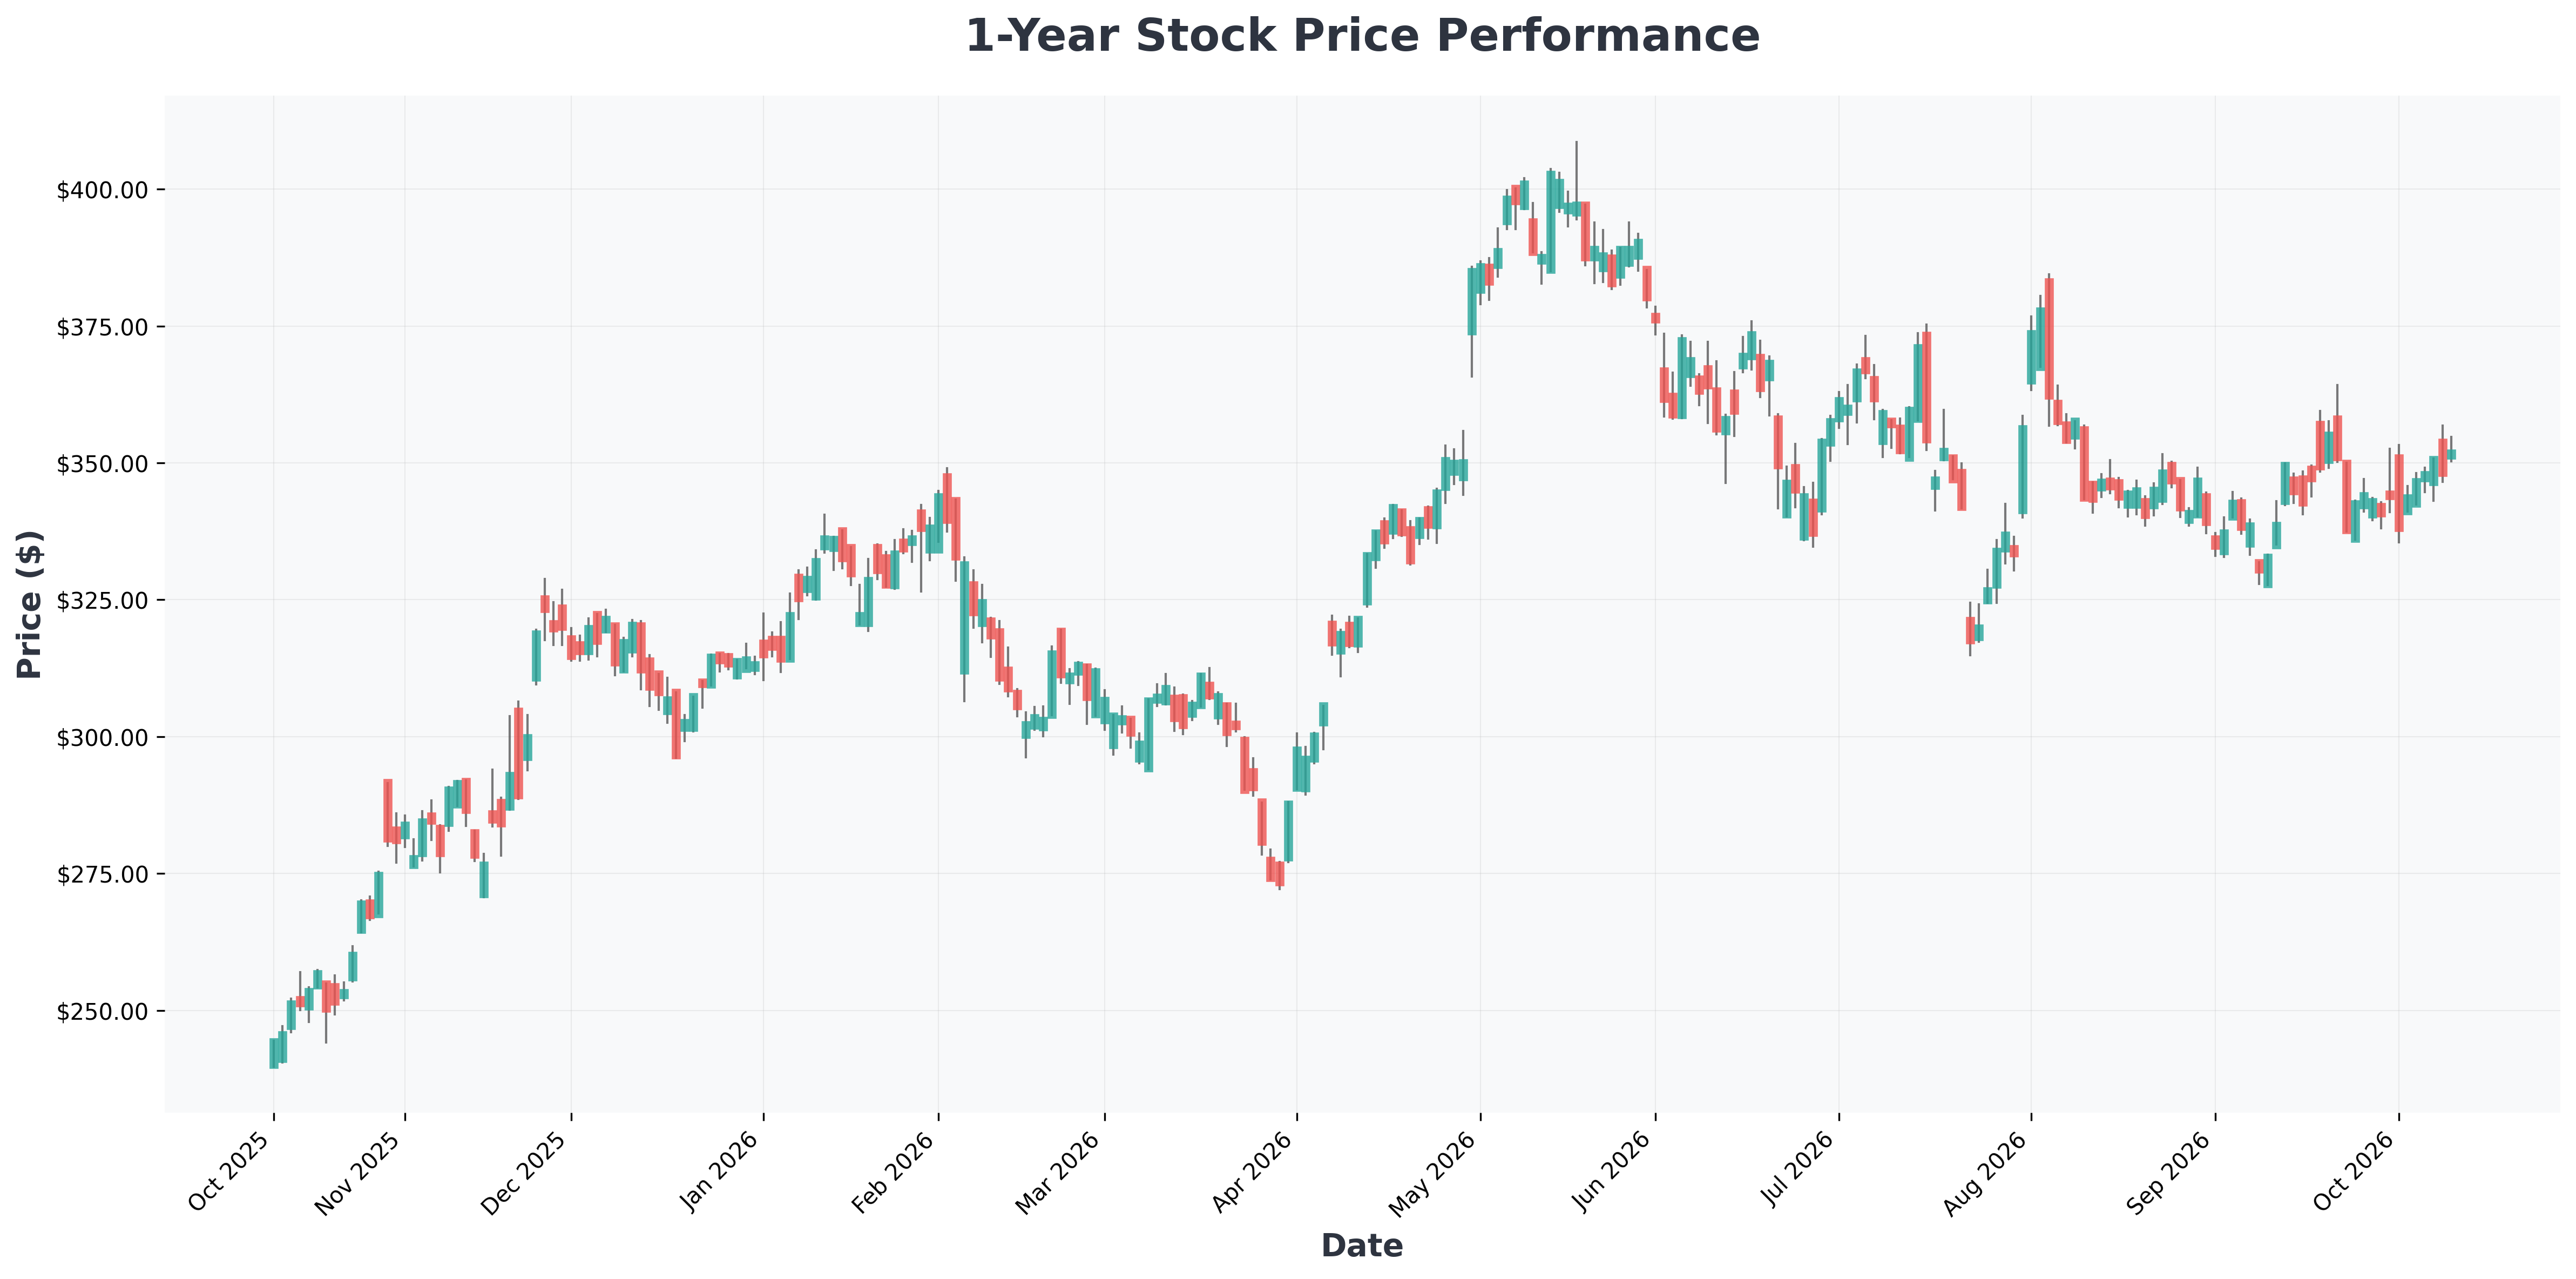
ASML is currently trading around $1,750, roughly 12% below its 52-week high of $1,999.96 and well above the 52-week low of $946.11. Historically, pullbacks of this magnitude in ASML have coincided with accumulation zones during prior capex upcycles — though past performance never guarantees future results.
The bull and bear case for ASML are both legitimate. Here is how the debate is shaping up on trading desks.
📊 In-Depth Fundamental Analysis
| Company | Share Price | P/E Ratio | P/B Ratio | ROE | Operating Margin (OPM) | Revenue Growth |
|---|---|---|---|---|---|---|
| ASML (ASML) | $1,750 | 56.81 | 1520.28 | 53.94% | 37.06% | 21.30% |
| GOOG (Alphabet) | $349 | 17.51 | 6.86 | 48.68% | 34.03% | 24.20% |
| GOOGL (Alphabet) | $353 | 17.70 | 6.93 | 48.68% | 34.03% | 24.20% |
| INTC (Intel) | $101 | 0.00 | 5.84 | -10.71% | 12.19% | 25.40% |
| MSFT (Microsoft) | $541 | 30.15 | 9.09 | 34.04% | 45.11% | 17.70% |
| NVDA (NVIDIA) | $226 | 28.61 | 23.87 | 117.21% | 66.24% | 105.90% |
| TSM (Taiwan) | $444 | 32.29 | 91.48 | 39.97% | 60.34% | 36.00% |
Scenario Planning: Where ASML Goes From Here
🟢 Best-Case Scenario
- Q3 beat + raised guidance on High-NA EUV orders
- Intel and Samsung ramp ahead of schedule
- TSMC pulls forward its 2030 High-NA timeline
- Potential path: Re-test of the $2,000 range and new all-time highs
🔴 Worst-Case Scenario
- Memory capex slowdown drags into 2027
- New export restrictions on advanced lithography to key markets
- Intel Foundry stumbles again, delaying High-NA adoption
- Potential path: Retest of the $1,400–$1,500 support zone
The Bottom Line 🎯
Nvidia designs the brains of AI. TSMC builds them. But ASML builds the machines that make both possible. That is not a hype story — it is a structural chokepoint in the AI supply chain.
For long-term investors, ASML is not a flashy trade. It is the quiet toll booth on the AI highway. And toll booths, historically, get paid either way.
⚠️ Risk reminder: Semiconductor equipment is a cyclical, capital-intensive business. Position sizing and time horizon matter more here than in most AI names. Do your own due diligence before acting.