Nike Loses Its S&P 100 Seat 📌
S&P Global confirmed that Nike (NKE) will be dropped from the S&P 100 on Sept. 21 as part of its quarterly rebalancing. Honeywell Aerospace, Simon Property Group, and Colgate-Palmolive are also out, while Dell, Palo Alto Networks, Arista Networks, and SanDisk take their places.
The removal isn't about size alone — it's about relevance. Nike now ranks as the 213th-largest S&P 500 component by weight, and it sits at the bottom of the iShares S&P 500 100 ETF. That's a stark fall from grace for a brand that once defined athletic blue-chip investing.
🚨 Key takeaway: Index removal is a mechanical event, but the underlying reason — deteriorating fundamentals — is what investors should be watching.
Why Nike Is Losing Its Blue-Chip Status 🔍
The S&P 100 isn't just the 100 biggest companies — it's a curated list of sector-defining leaders. Nike held its spot for years on brand prestige, not market cap. That premium no longer holds.
The Numbers Tell the Story
- Market cap: ~$55B, a fraction of its 2021 peak
- Operating margin: Collapsed from low-to-mid teens pre-pandemic to under 9%
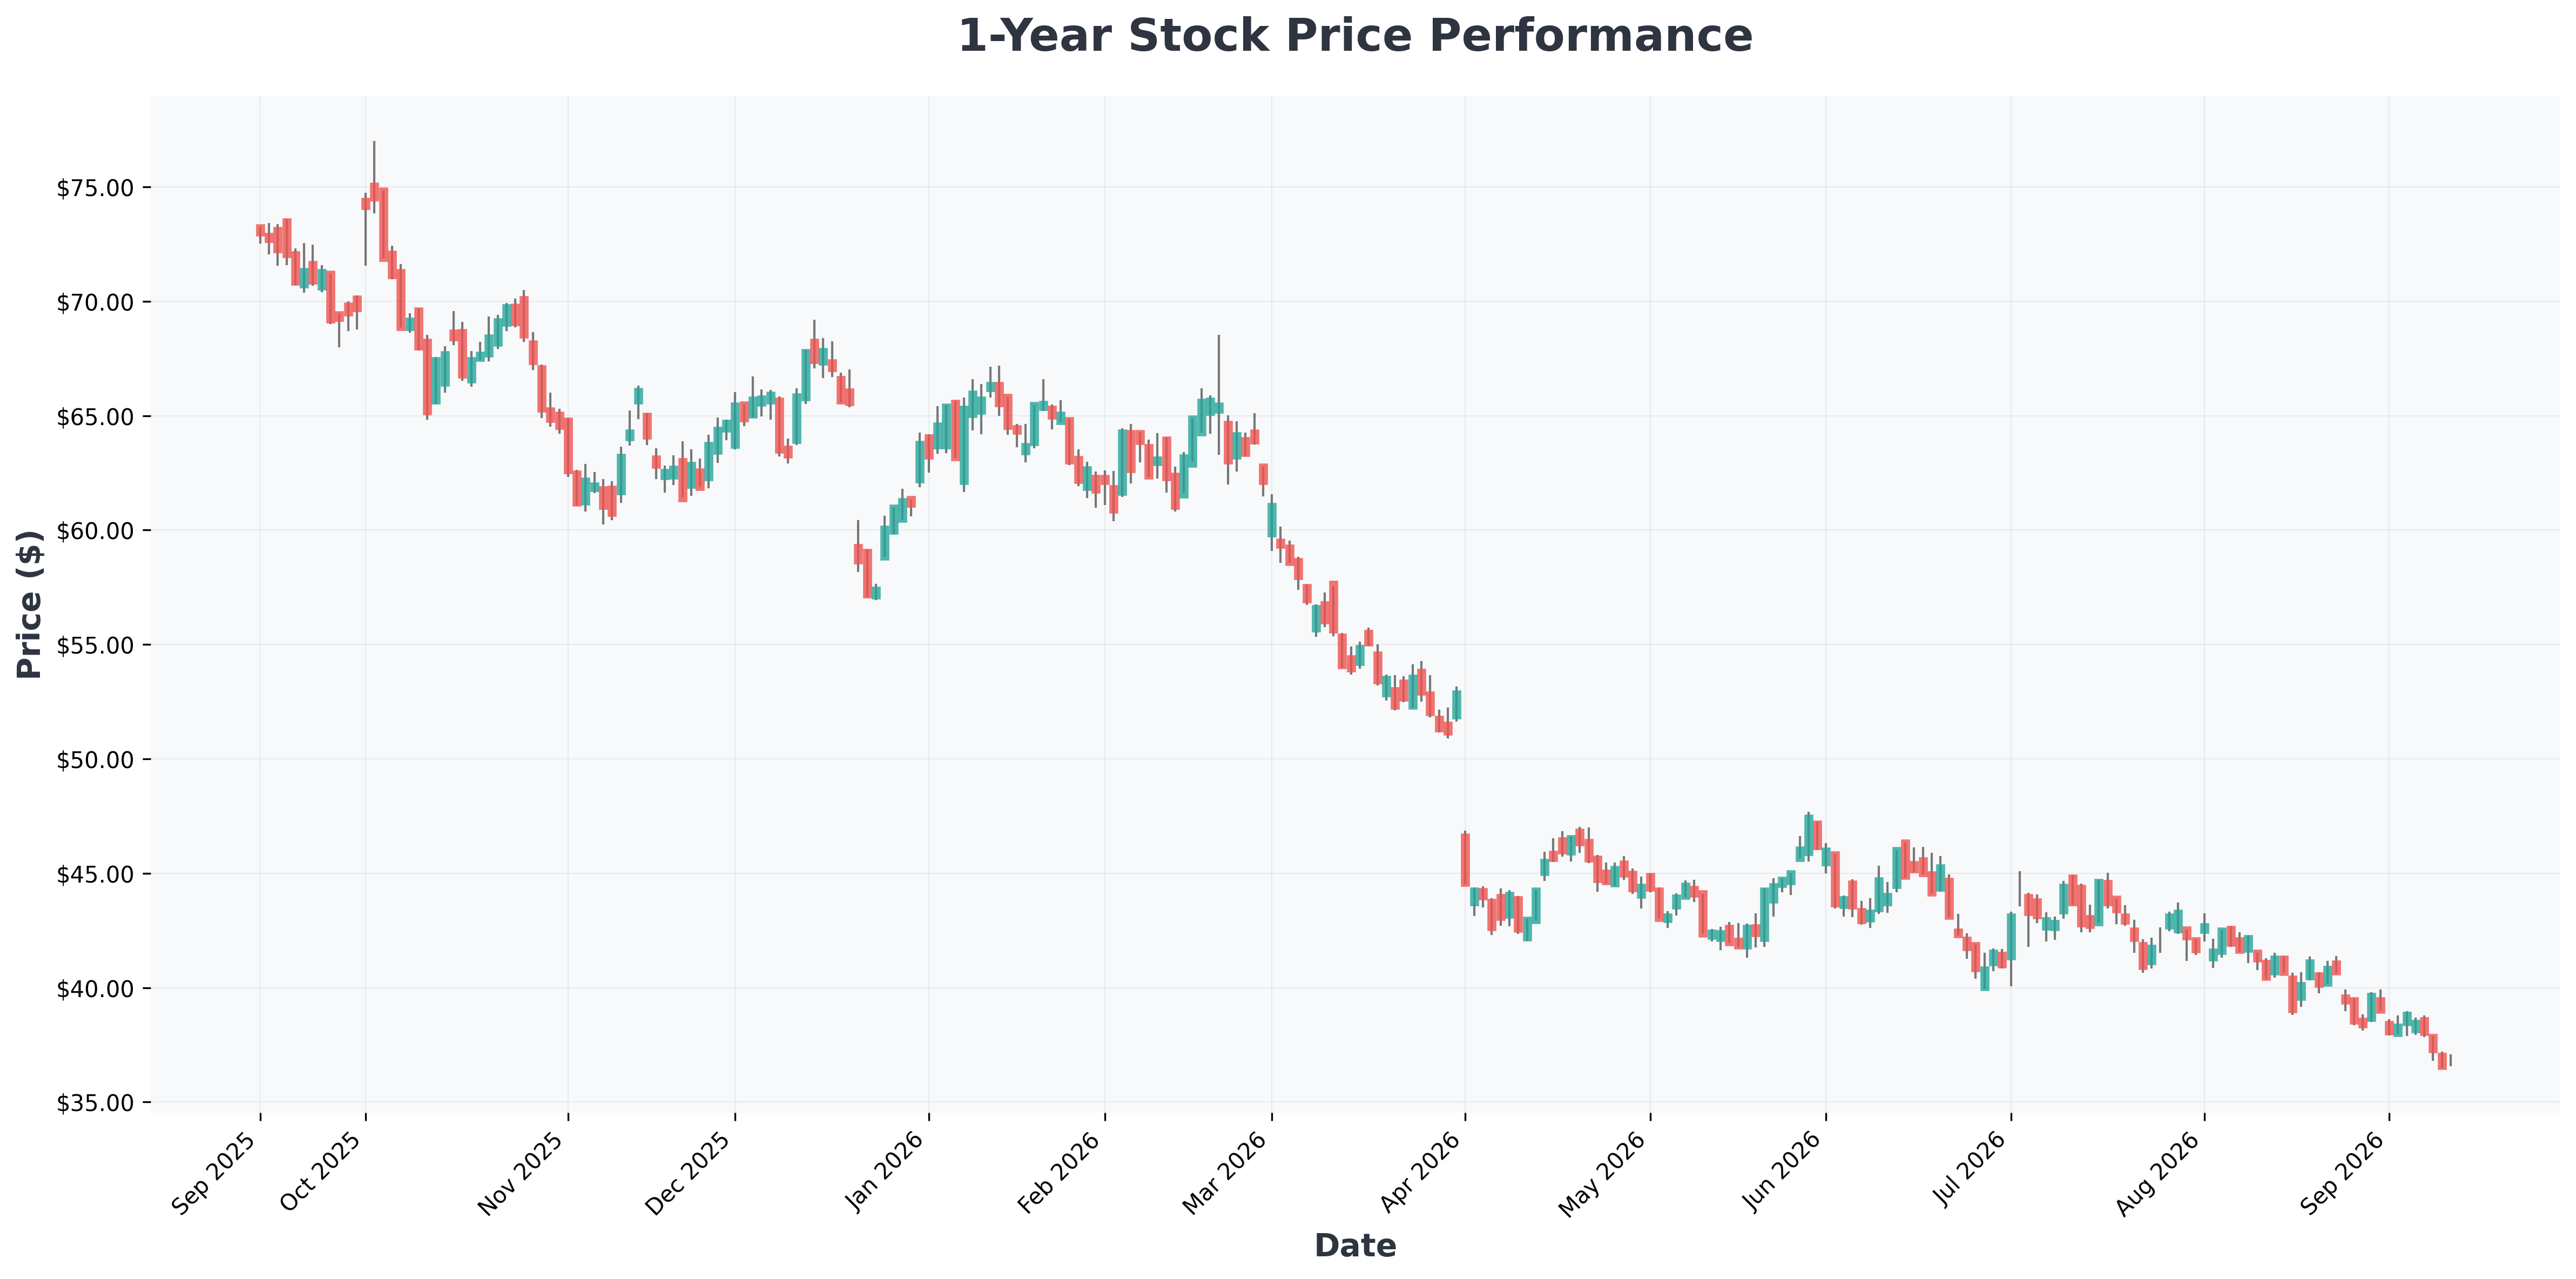
- 52-week range: $36.55 – $76.97 — trading near the bottom
- Dividend yield: 4.46%, unusually high for a growth name (a warning sign)
What Went Wrong
Nike's issues are stacked: supply chain missteps, a botched direct-to-consumer pivot, slowing China growth, tariff pressure, cautious U.S. consumer spending, and fierce competition from On, Hoka, and Adidas.
The Win Now turnaround plan has produced some green shoots — wholesale revenue grew 4% YoY in fiscal 2026 with double-digit North America growth — but the structural headwinds haven't cleared.
The Nike story is splitting the market right now. Here's how bulls and bears are framing it:
The Dow Jones Question 🎯
Here's where it gets uncomfortable for Nike bulls. After Alphabet replaced Verizon in June, Nike became the lowest-ranked component in the price-weighted Dow Jones Industrial Average. With only 30 seats, the Dow is far more exclusive than the S&P 100 — and Nike now represents a mere 0.4% of the index.
Who Could Take Nike's Seat?
The Dow has pivoted hard toward tech to mirror the modern economy — adding Nvidia and Amazon in 2024, Alphabet in 2026. Candidates waiting in the wings include:
- Broadcom — AI infrastructure powerhouse
- Meta Platforms — megacap with dominant ad moat
- Tesla / SpaceX — pending any merger scenario
Historical Parallel
Looking back at past Dow ejections — GE in 2018, ExxonMobil in 2020 — the pattern is consistent: once a legacy name loses its sector leadership premium, removal follows within 12–18 months. Nike's chart is tracing a similar trajectory, with the stock forming a long-term downtrend below its 200-week moving average. Unless a decisive break above $50 materializes, the technical setup reinforces the bear case.
📊 In-Depth Fundamental Analysis
| Company | Share Price | P/E Ratio | P/B Ratio | ROE | Operating Margin (OPM) | Revenue Growth |
|---|---|---|---|---|---|---|
| SPG (Simon) | $205 | 14.46 | 15.08 | 120.51% | 46.02% | 19.50% |
| GOOGL (Alphabet) | $338 | 16.98 | 6.65 | 48.68% | 34.03% | 24.20% |
| GOOG (Alphabet) | $335 | 16.83 | 6.59 | 48.68% | 34.03% | 24.20% |
| SNDK (Sandisk) | $1,633 | 22.12 | 15.47 | 91.64% | 78.47% | 371.60% |
| DELL (Dell) | $567 | 33.00 | -256.46 | 0.00% | 12.02% | 57.70% |
| CL (Colgate-Palmolive) | $87 | 34.17 | 293.24 | 267.37% | 20.97% | 4.90% |
| NKE (Nike,) | $37 | 17.52 | 3.67 | 22.14% | 12.69% | -1.10% |
| PANW (Palo) | $331 | 826.62 | 9.83 | 1.74% | 5.04% | 34.40% |
| ANET (Arista) | $200 | 63.36 | 17.01 | 31.48% | 45.39% | 37.70% |
Scenario Analysis: Where Does Nike Go From Here? 📊
| Scenario | Trigger | NKE Impact |
|---|---|---|
| Bull Case 🐂 | Win Now delivers margin recovery above 12%, China stabilizes, Dow retains Nike for dividend prestige | Re-rating toward $55–$60; dividend safe |
| Base Case ⚖️ | Modest wholesale growth, flat margins, Dow removal announced within 12 months | Range-bound $34–$42; yield supports floor |
| Bear Case 🐻 | China deteriorates further, tariffs bite, dividend coverage tightens | Break below $34; Dow exit accelerates selling |
The Bottom Line
Nike is no longer a "set it and forget it" blue chip. The 4.3% dividend looks attractive, but if free cash flow keeps shrinking, that payout becomes a liability rather than a cushion. With the S&P 500 and Dow near all-time highs, the market has little patience for laggards.
Investors should wait for concrete evidence of a sustained turnaround — two consecutive quarters of margin expansion and stabilizing China revenue — before treating this as a value play. Until then, the index exits are likely to keep coming. ⚠️