The S&P 500's Quiet Concentration Problem 📌
The S&P 500 has delivered total returns of nearly 18% over the past 12 months, well above its historical average of roughly 10%. Much of that outperformance traces back to one sector: technology, which has surged 46% in just six months while every other industry combined managed only ~11%.
That divergence is impressive — and it is exactly what should make long-term investors pause. When a handful of names drive the index, the index stops behaving like a diversified basket and starts behaving like a concentrated bet.
Key takeaway: The S&P 500 is no longer a broad-market proxy. It is increasingly an AI-infrastructure proxy.
How Concentrated Is the Market, Really? 🐻
As of this writing, the S&P 500 carries a total valuation of roughly $70.4 trillion. The top 10 holdings alone account for $27.4 trillion — about 39% of the entire index. Those ten names, in order, are:
- Nvidia
- Apple
- Alphabet
- Microsoft
- Amazon
- Meta Platforms
- Broadcom
- Tesla
- Micron Technology
- Berkshire Hathaway
According to S&P Global data, the last time concentration was this extreme was 1965 — but back then the top holdings (AT&T, General Motors, IBM, DuPont) spanned telecom, autos, tech, and chemicals. Today, nearly every top name is either directly or tangentially an AI development play.
Amazon, Meta, Microsoft, and Alphabet collectively spent over $300 billion on data centers in the first half of 2026 — and those four alone are expected to account for nearly half of global AI infrastructure spending this year.
The Break-Even Math Nobody Wants to Do 🎯
Goldman Sachs estimates that hyperscalers will need to generate at least $300 billion in AI revenue over the next few years just to break even — and roughly $1 trillion per year to earn healthy margins.
That is not a forecast. It is a hurdle. And it is the single number that determines whether the current concentration is justified or dangerous.
Historical Parallel: 1994–2000 vs. 2022–Today
| Period | Top 10 Weight | Shiller CAPE | Outcome |
|---|---|---|---|
| Jun 1994 | 17% | ~20 | — |
| Jun 2000 | 26%+ | 44 (record) | S&P 500 lost ~50% over 2 years |
| Late 2022 | ~26% | ~28 | — |
| Today | 39% | 40+ | Unknown |
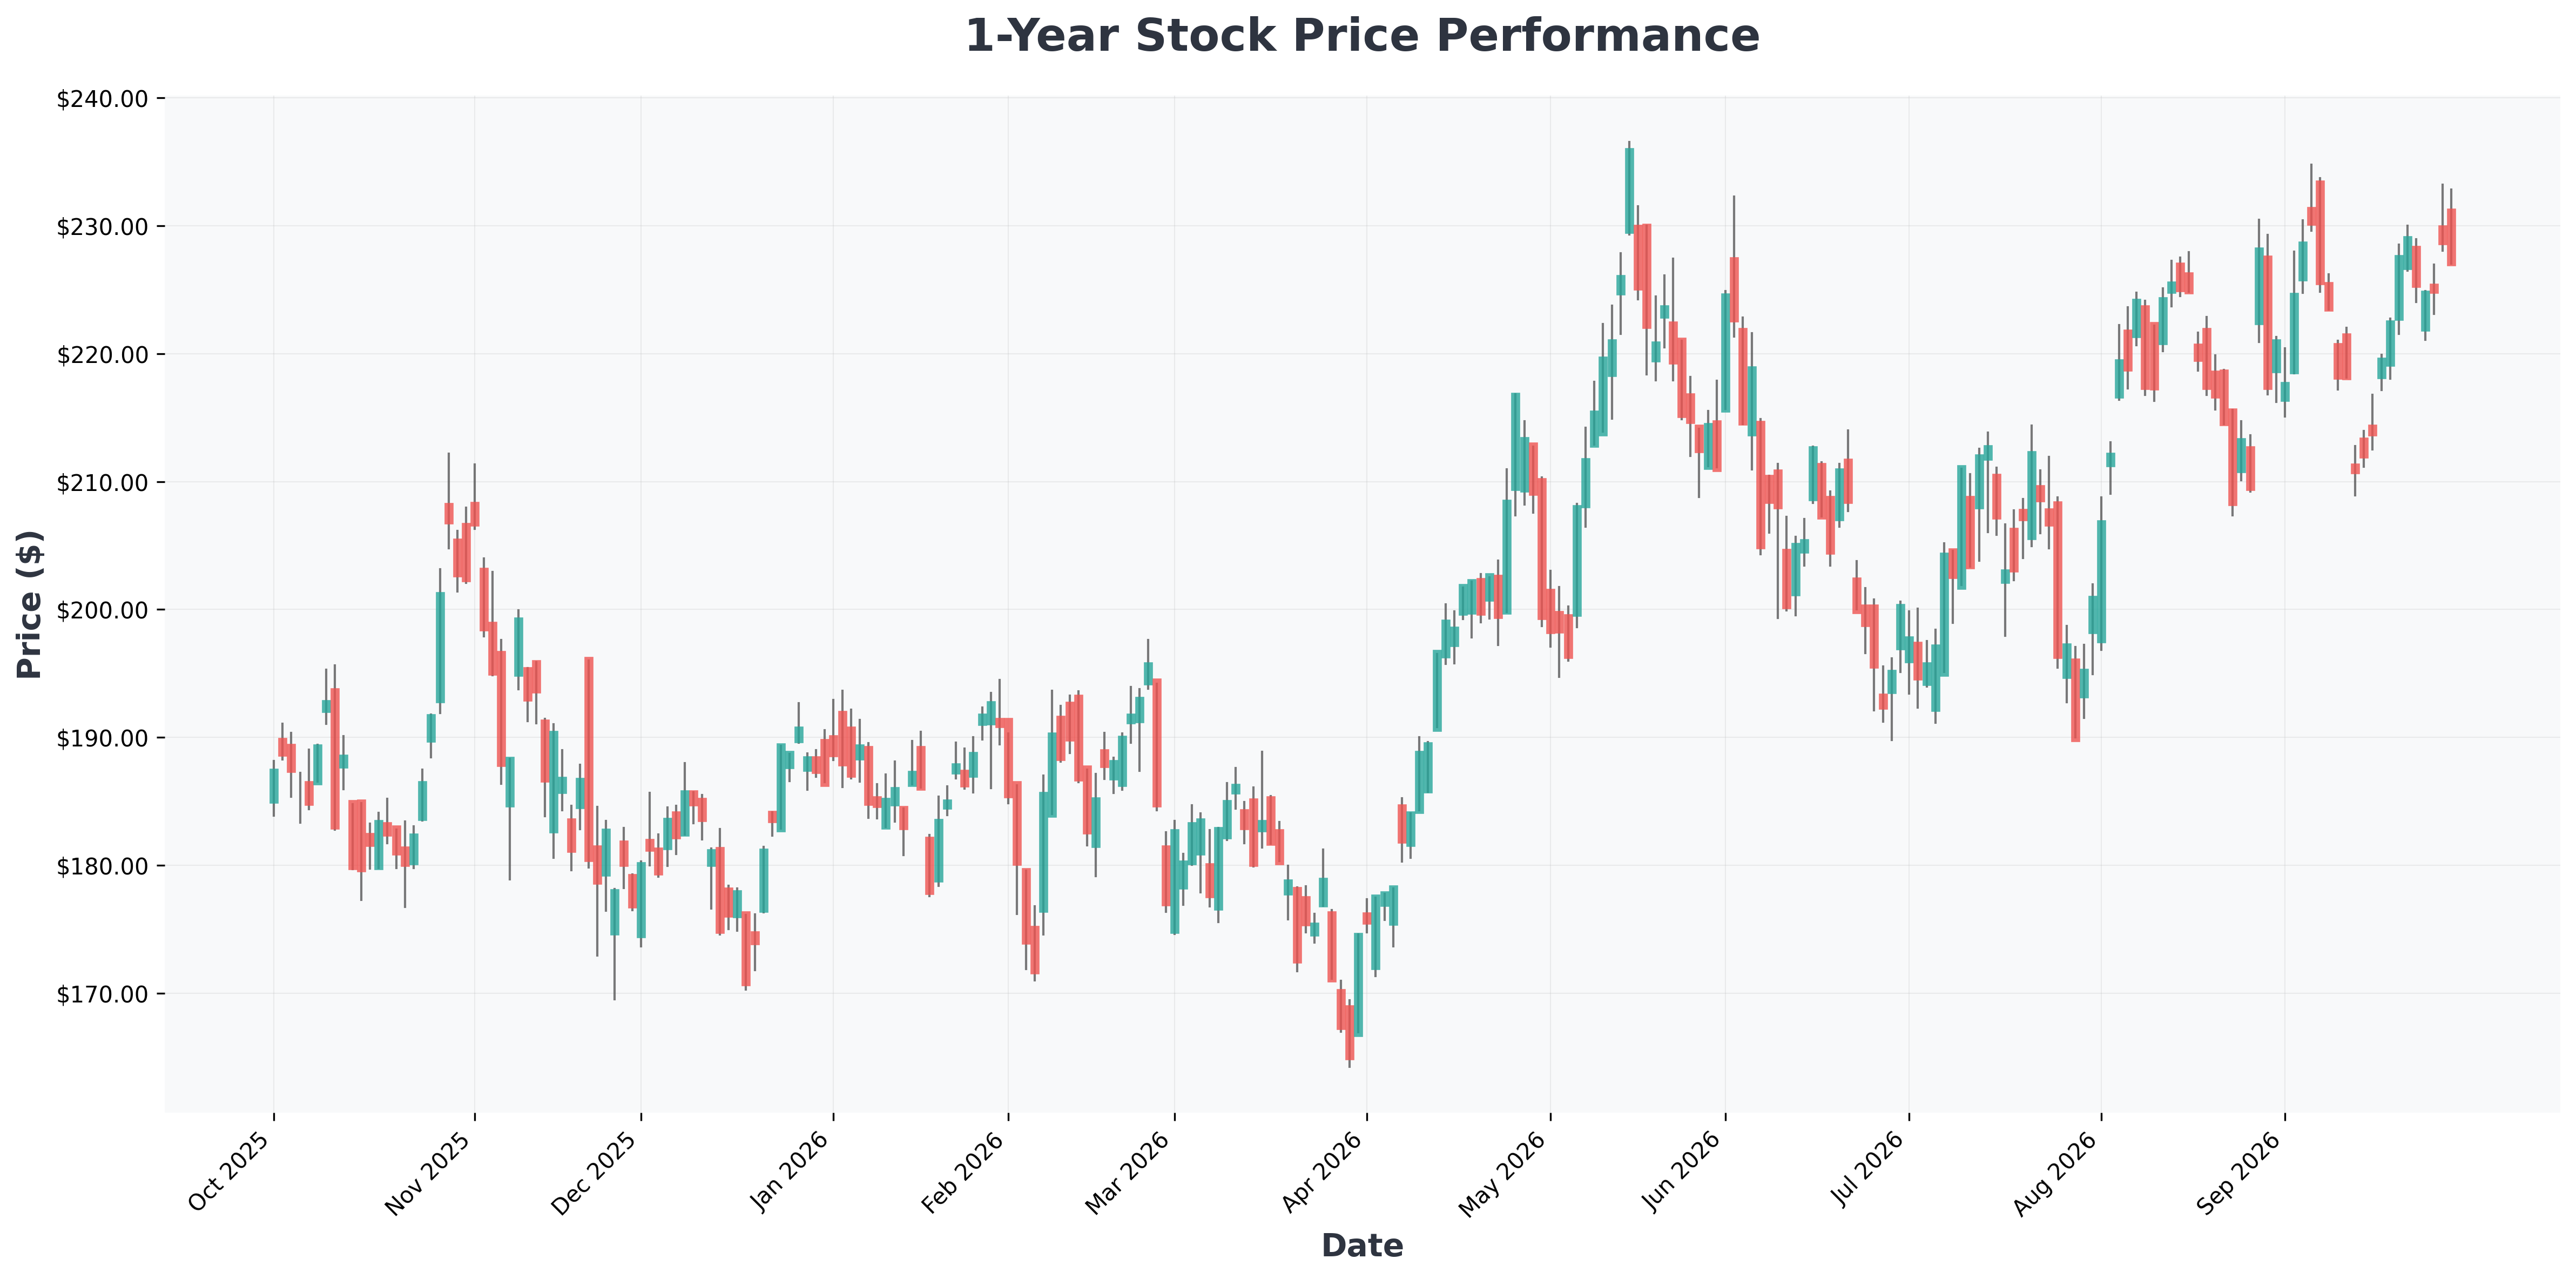
The current bull market has pushed concentration from 26% to 39% in under four years — a faster spike than the dot-com era. Meanwhile, the Shiller CAPE ratio sits above 40, closing in on the all-time high of 44 set in 2000.
Backtesting insight: In every historical instance where the S&P 500's top-10 weight exceeded 30% while CAPE was above 35, forward 3-year real returns were negative. That sample is small, but the pattern is consistent.
Market participants are sharply divided on whether this concentration is a warning sign or a structural shift. Here is how the debate breaks down:
📊 In-Depth Fundamental Analysis
| Company | Share Price | P/E Ratio | P/B Ratio | ROE | Operating Margin (OPM) | Revenue Growth |
|---|---|---|---|---|---|---|
| AAPL (Apple) | $333 | 38.15 | 45.25 | 148.75% | 32.62% | 16.40% |
| AMZN (Amazon.com,) | $249 | 20.04 | 4.87 | 30.56% | 13.69% | 19.60% |
| AVGO (Broadcom) | $351 | 45.26 | 16.82 | 44.25% | 54.31% | 85.50% |
| GOOG (Alphabet) | $341 | 17.09 | 6.69 | 48.68% | 34.03% | 24.20% |
| GOOGL (Alphabet) | $344 | 17.26 | 6.76 | 48.68% | 34.03% | 24.20% |
| META (Meta) | $725 | 27.34 | 7.07 | 29.85% | 34.83% | 28.00% |
| MSFT (Microsoft) | $513 | 28.54 | 8.61 | 34.04% | 45.11% | 17.70% |
| MU (Micron) | $1,065 | 24.10 | 11.94 | 66.64% | 80.37% | 345.70% |
| NVDA (NVIDIA) | $228 | 28.87 | 24.08 | 117.21% | 66.24% | 105.90% |
| TSLA (Tesla,) | $355 | 325.51 | 16.13 | 4.67% | 1.41% | 25.50% |
Scenario Planning: What Happens Next? 🤔
No two bear markets are identical, and no indicator predicts the future with certainty. But investors should plan for both paths.
🟢 Best-Case Scenario
- Hyperscalers hit the $1 trillion annual AI revenue threshold by 2028.
- Concentration stays elevated but is earnings-justified.
- S&P 500 grinds higher; long-term investors are rewarded.
🔴 Worst-Case Scenario
- AI revenue plateaus below break-even.
- Capex write-downs hit mega-cap earnings.
- Index concentration amplifies the drawdown — a 30–50% correction becomes plausible.
The Silver Lining 📈
Since early 1999 — when valuations began to soar into bubble territory — the S&P 500 has still delivered total returns of nearly 1,000%. The index has repeatedly recovered from severe volatility.
The playbook: Long-term investors have the most to gain regardless of what the next few years bring. Staying invested, rebalancing away from extreme concentration, and avoiding panic selling remain the historically proven defenses. This is not investment advice — every portfolio's risk tolerance is different.